LNG Canada Doubles Capacity as Asia Looks Beyond the Gulf
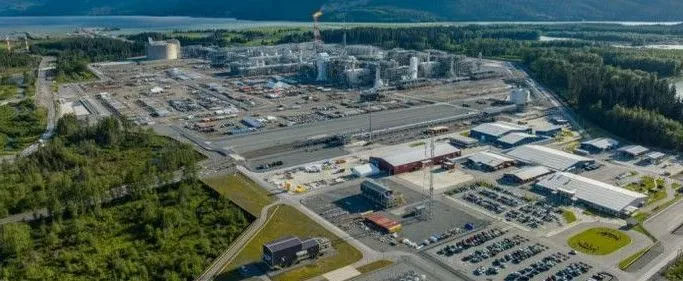
Last month, Shell (NYSE:SHEL), alongside Malaysia’s PETRONAS, China’s PetroChina, Mitsubishi Corporation and KOGAS, officially approved the Final Investment Decision (FID) for the LNG Canada Phase 2 expansion project, doubling the facility’s capacity to 28 million tons per annum (mtpa) and reinforcing the country’s potential as a significant long-term supplier to Asian markets. Together with Cedar LNG and Woodfibre, both currently under construction, Canada is expected to export 33 mtpa of LNG by the end of the current decade. According to Wood Mackenzie, Canada is well positioned to address Asia’s growing demand for long-term, lower-carbon liquefied natural gas (LNG) thanks to its vast resource scale, geographic proximity and short Pacific shipping routes. However, Wood Mac has also warned that Canada faces a narrowing window of opportunity as global competition for capital and market share intensifies.
“For Asian buyers, Canada offers something that is increasingly rare in global LNG markets: a combination of resource scale, Pacific Basin access and short shipping routes,” said Joshua Ngu, Vice Chairman, Asia Pacific at Wood Mackenzie. “Canada’s resource advantage is real, but realizing its full potential will depend on competitiveness, execution and timely project delivery.”
Finally, Canadian LNG can be cleaner, aligning with the net-zero targets of buyers in Japan and South Korea. Cedar LNG is designed to run entirely on renewable hydroelectricity from BC Hydro in place of gas-fired turbines, drastically cutting greenhouse gas emissions. LNG Canada uses gas to drive its liquefaction trains and draws on BC Hydro for about a fifth of its energy needs.
That said, WoodMac notes that even with the addition of projects such as the 12 mtpa Ksi Lisims LNG, Canada will fall well short of Prime Minister Mark Carney’s long-term “energy superpower” agenda of achieving 100 mtpa of LNG export capacity. Meanwhile, Canada’s window to capture the uncontracted share of Asia’s expanding LNG demand is narrowing, with American projects like CP2 LNG, Commonwealth LNG and Delfin FLNG 1, all of which reached FID this year, set to extend U.S. dominance in global LNG exports.
Further, new infrastructure and LNG export projects across Africa, Latin America and Australia are progressing rapidly, providing price-sensitive Asian buyers with diverse portfolios. To wit, emerging players like Mozambique, Nigeria, and Mauritania/Senegal are developing massive offshore fields and Floating LNG (FLNG) facilities, positioning the continent as a major supplier to both Europe and Asia. Meanwhile, projects in countries like Mexico (utilizing cheap U.S. pipeline gas for export from its Pacific coast) and Argentina (tapping the Vaca Muerta shale basin) would open faster shipping routes to Asian markets.
This post appeared first on https://oilprice.com